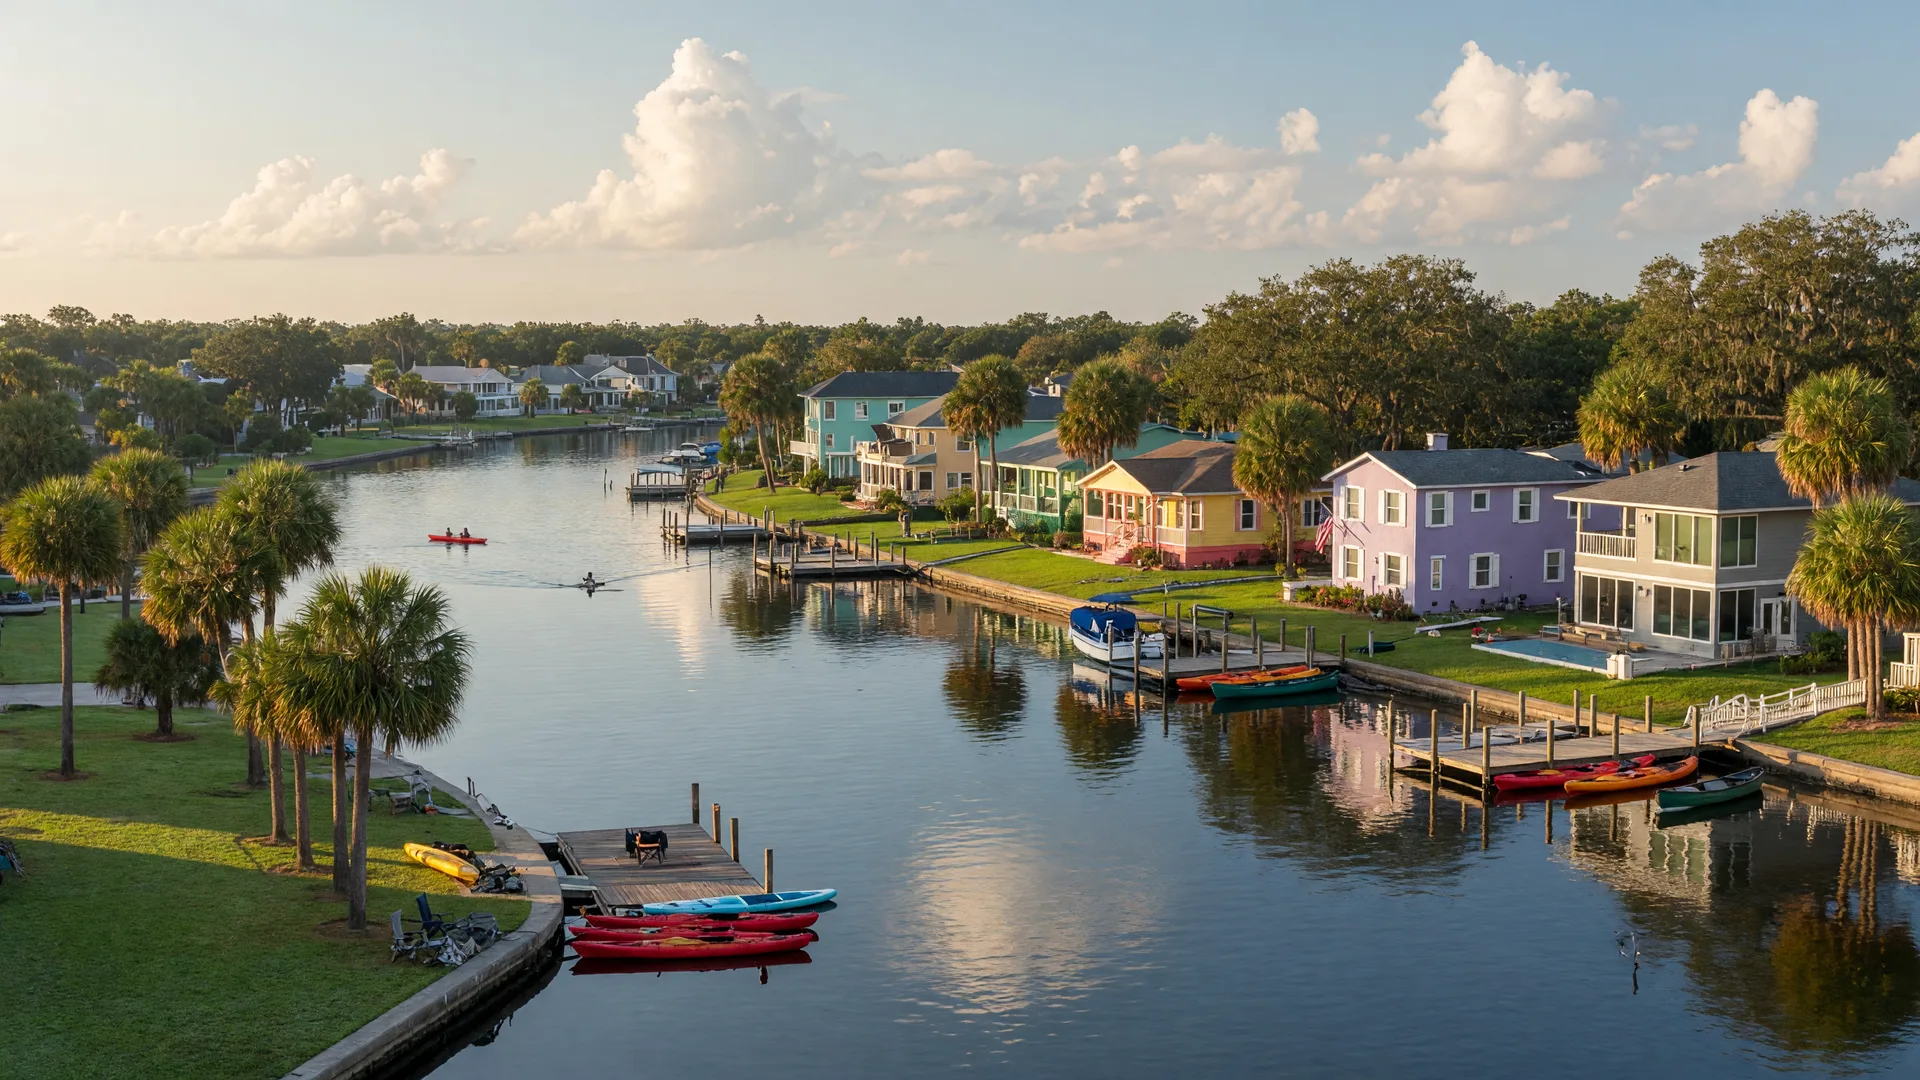
In New Port Richey right now, most homes sell slightly below asking price, buyers have more negotiating room than they have had in years, and the flood-insurance question is one of the most important numbers to check before you make an offer. Here is what the latest market data actually shows, how to negotiate for the real conditions on the ground, and what the Cotee River lifestyle costs on top of the mortgage.
We're Paul and Denise Virgadamo, a husband-and-wife team with over 45 years of Tampa Bay roots and more than 1,000 homes sold across Pasco, Pinellas, and Hillsborough Counties. New Port Richey is home turf for us, and we work its neighborhoods every single week. This guide answers the questions buyers ask us most here, with real numbers, not the listing price on the sign.
What Buyers Actually Pay Across New Port Richey Right Now
The first question almost every buyer asks is whether asking price is the real price. In New Port Richey today, the honest answer is: usually a little less, and how much less depends on which part of town you are shopping. The city spans five ZIP codes, 34652 through 34656, and each one has its own price point. Downtown New Port Richey, including Sims Park and the Historic Downtown District, sits in the 34652 ZIP, where historic bungalows and riverfront cottages trade at a very different level than the newer subdivisions in the 34655 area. Citywide, the market leans slightly in the buyer's favor, with most homes closing at or below asking and the negotiating margin varying neighborhood by neighborhood.
The trackers show that spread clearly. RealtyTrac's trailing twelve-month medians, as of 2025, put the 34652 downtown ZIP around $250,000, the 34653 established neighborhoods around $265,000, the 34654 ZIP around $335,000, and the 34655 area near $400,000. Redfin's 34655 data, updated through August 2026, tells the same story from a different angle: a median sale price around $410,000 with a sale-to-list ratio of about 97.7%, meaning the typical home there closes roughly 2.3% below asking. Citywide, Redfin reports the average New Port Richey home sells about 4% below list. These figures move month to month and vary by source, so treat them as a directional map of the market, not a price list.
That spread is not a sign of weakness in the market. It is a sign that asking prices now carry a little negotiating margin, the way they did before the post-2020 frenzy. Houses that are priced realistically are still moving, typically in about three weeks on market in the 34655 data, while overpriced listings are the ones that sit, get their price cut, and end up negotiating from a weaker position. The practical takeaway: treat the asking price as a starting point for a conversation, not as a fixed number, and ground that conversation in what recent similar homes actually closed for in the specific ZIP you are shopping.
The Negotiating Room Buyers Have in 2026
In the hot market, buyers made offers over asking, waived inspections, and felt lucky to get any response. That is not the market New Port Richey is running right now. When sold listings in the area are closing 5% to 14% below list in many cases, the tables have genuinely turned, and sellers know it. Motivated sellers across west Pasco are regularly offering closing-cost credits, mortgage rate buydowns that lower your payments for the first few years, and repair credits after inspection to get deals done.
- Shop with sold prices, not asking prices. Your agent should pull the last six or eight comparable sales, what they listed for, what they closed for, and how long they took. That is the real market, and it is what your offer should be built on.
- Ask for concessions in writing. A closing-cost credit or a rate buydown is a normal part of 2026 negotiations here, and sellers expecting a negotiation are often willing to structure one before you ever reach the inspection stage.
- Keep your contingencies. Inspection, appraisal, financing, insurance: in this market you do not have to waive them to compete, and a smart seller prefers a buyer with protection they can actually close with.
- Be pre-approved with the real payment in mind. In flood-aware neighborhoods, your pre-approval should already account for taxes and flood insurance, not just principal and interest, so the offer you make is an offer you can close.
Negotiating room is not a blank check, and we never advise lowballing a well-priced home. But in a market where the average home closes below list, a fair, well-supported offer with a reasonable inspection period is simply how business is done here in 2026.
Why the Downtown and Cotee River Pull Buyers In
The reason people end up choosing New Port Richey rarely comes down to price alone, it comes down to what the price buys. Sims Park is the town's living room on the Cotee River: a riverfront amphitheater, splash pad, walking paths, and a calendar of concerts, movie nights, and festivals through the year. The restored Hacienda Hotel anchors a downtown that has come back to life, with markets, dining, and events in Railroad Square, from the Friday night farmers market to the Fourth Friday street fair. If you are weighing what life would actually look like here, our New Port Richey community guide walks through the neighborhoods, dining, parks, and events in detail.
The neighborhoods fit different buyers. The Downtown Riverfront District offers historic bungalows and Craftsman homes on tree-shaded streets, walkable to Sims Park and the amphitheater, and it is where many first-time buyers and empty nesters land. Along Grand Boulevard and into Gulf Harbors, homes range from colorful cottages to larger waterfront estates with private docks, where you can kayak from your backyard toward the Gulf. James E. Grey Preserve puts 80 acres of wetlands within walking distance of downtown, and the Cotee River Paddling Trail runs from downtown out to the Gulf, which is why you see kayaks and paddleboards out most mornings.
What buyers should understand before they fall in love with a waterfront address is the second number in this guide: what the water costs to insure, because that number shapes the real monthly payment more than any other variable in this town.
The Flood Zone and Insurance Question Every Buyer Should Ask
New Port Richey is a river town on the Gulf coast, and that identity comes with a floodplain. The City of New Port Richey reports that roughly 44% of the city sits in a FEMA Special Flood Hazard Area, and that nearly all properties near the Gulf and along the Pithlachascotee River can flood on a high tide with a strong west wind, even on a clear day. The dominant mapped zones are Zone AE along the river and the Gulf Harbors canals, Zone VE along the most exposed waterfront, and Zone X for higher, lower-risk inland areas. Pasco County adopted new Flood Insurance Rate Maps in early 2020, so the zone at any specific address is a parcel-level question, not a neighborhood rumor.
- If the home is in an A or V zone and you use a federally backed loan (FHA, VA, Fannie Mae, Freddie Mac), flood insurance is mandatory. This is not optional, it is a closing requirement, and lenders will verify coverage before you sign.
- Ask for the elevation certificate. It documents the lowest floor height relative to the base flood elevation, and it is the single most useful document a riverfront buyer can request. In Pasco's coastal AE zones, base flood elevations around 10 to 11 feet are common, so a home built or raised to that standard is in a very different insurance position than one that is not.
- Budget for the premium, not just the mortgage. Pasco County had roughly 23,500 active flood policies with an average premium around $1,200 a year, with Zone AE properties averaging closer to $1,665 and Zone VE close to $2,305 under FEMA's Risk Rating 2.0 parcel-specific pricing. Your actual quote depends on elevation, construction, and claims history, which is why we ask for insurance quotes before we ever draft an offer.
- Even Zone X is worth insuring. Roughly a quarter of National Flood Insurance Program claims come from low-to-moderate-risk areas, and both New Port Richey and Port Richey participate in FEMA's Community Rating System, which earns residents premium discounts.
- Know the 50% rule. If a building in the floodplain is substantially improved or damaged by more than 50% of its market value (Pasco's threshold is 49%), it must be brought up to current flood standards, which can mean elevation. Ask your agent about a property's elevation history before you commit.
None of this is a reason to avoid New Port Richey, waterfront living here is a genuine bargain compared with much of coastal Florida. It is a reason to buy with your eyes open, because an informed buyer can often find a home that is already elevated, already flood-insured at a reasonable rate, and already priced in a negotiable range. The buyers who get burned are the ones who find out about the floodplain after closing, not before.
How to Shop New Port Richey Like an Advisor
If you are starting your search, here is the checklist we run with buyers before they look at their first New Port Richey listing:
- Get pre-approved with insurance in the number. Ask your lender to model taxes and flood insurance into your payment so the price you qualify for is the price you can actually carry.
- Pull the flood map for every address you like. FEMA's FIRMette tool and Pasco County's records show the zone before you invest a weekend in touring. We pull these for clients on the first pass, not the day before the offer.
- Compare the downtown bungalow to the waterfront property honestly. A home within walking distance of Sims Park may need less insurance, less maintenance, and no dock, and the monthly savings often pay for a lot of kayak trips.
- Ask for the seller's paperwork. Elevation certificates, roof age and documentation, insurance claims history, and flood disclosures belong in the file before you negotiate, and a seller with paperwork wins your confidence.
- Put your offer together with contingencies and a real closing timeline. In a market averaging a few weeks on market, a clean, well-supported offer with a pre-approval is competitive without being reckless.
Tampa Bay overall sits in a balanced market in 2026, but New Port Richey is its own animal: some of the most affordable Gulf Coast living in west Pasco, a downtown that keeps getting younger, and a waterfront that demands respect. The buyers who do well here are the ones who treat it like a real estate town with real numbers, because it is.
The Bottom Line from Team Virgadamo
Here is the summary we would give our own family: in New Port Richey in 2026, plan to negotiate below asking, price your offer against real sold data, fall in love with the river lifestyle, and settle the flood-insurance question before you ever sign. Do those four things and this town can be one of the smartest purchases on Florida's Gulf coast.
Who you hire truly matters. We have bought, sold, and lived in this market for over 45 years, closed more than 1,000 homes, and we know the difference between a waterfront bargain and a waterfront headache. Start with our New Port Richey community guide, then let's look at your numbers together. We Live, Love & Sell Tampa Bay!
Ready to see what your budget buys on the Cotee River?
Let's pull the sold data, check the flood zone, and run the real monthly cost on the New Port Richey homes you love. Schedule a free, no-obligation consultation with Paul and Denise Virgadamo.
Explore our communities: