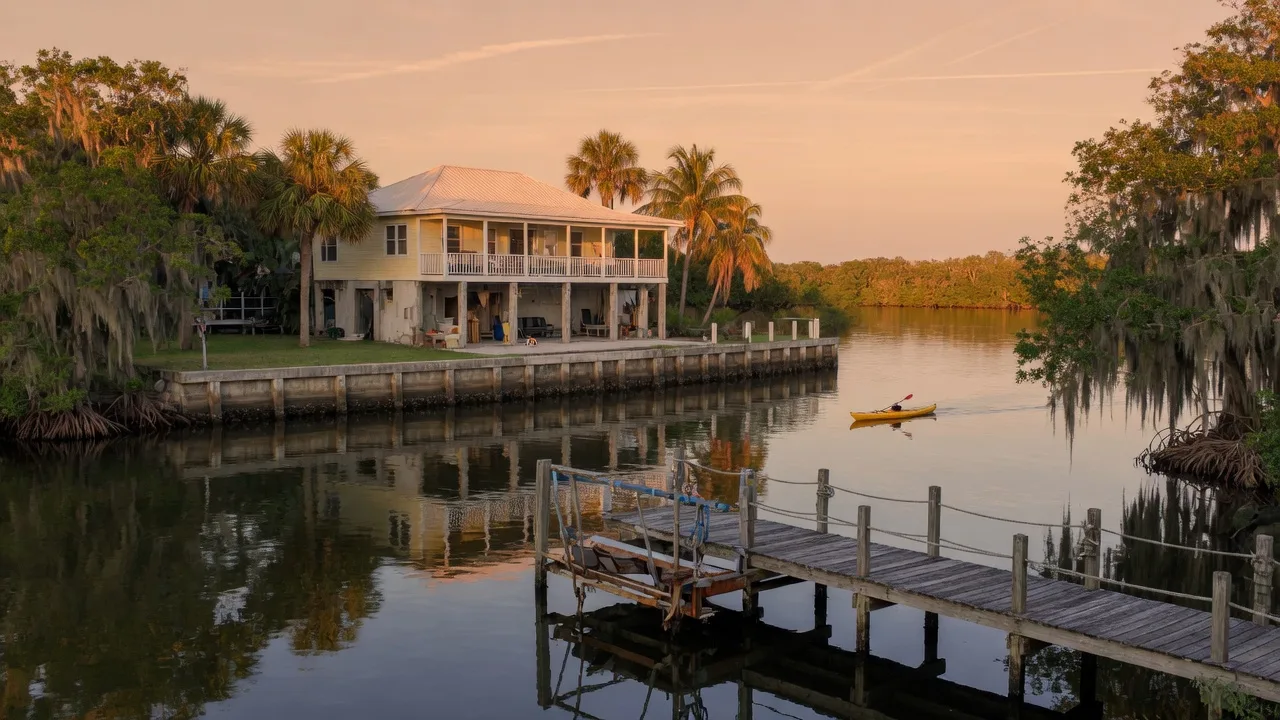
Should a flood zone keep you from buying in New Port Richey? Usually not, and if you insist on a completely flood-free address here, you might pass on a third of the city for no reason. Roughly 44% of New Port Richey sits inside FEMA's Special Flood Hazard Area, most of it along the Cotee River and the Gulf Harbors canals, and the question that matters is not the zone letter on a map. It is what that zone costs to insure at a specific address, what the home's elevation buys you, and how you build both into an offer you can actually close.
Is the Home You Are Looking At in a Flood Zone?
New Port Richey is a river town, and its flood map reflects it. The City of New Port Richey reports that roughly 44% of its land, about 1,307 of the city's 2,949 acres, sits inside a FEMA Special Flood Hazard Area, the 100-year floodplain. Within the city limits the mapped flood zones come down to two: Zone AE and Zone A, the riverine and coastal floodplains that carry a 1% annual chance of flooding, which works out to about a 26% chance over a 30-year mortgage. The rest of the city maps as Zone X, the moderate-to-low-risk floodplain where flood insurance is voluntary. The most exposed Gulf-front parcels sit just outside the city line in unincorporated Pasco County, where the map can look different, so check the exact parcel rather than assuming the neighborhood next door has the same zone.
That map is not neighborhood rumor; it comes from Pasco County's Flood Insurance Rate Maps, effective June 5, 2020. You can look up your own parcel with the county's Find My Flood Zone tool or FEMA's Flood Map Service Center, and the answer is always parcel-level. Two houses two blocks apart can sit in different zones, or in the same zone with very different premiums, which is why we tell every buyer to confirm the zone for the specific address before making an offer, never from a neighborhood reputation.
The neighborhoods line up predictably. Along the Downtown Riverfront District and the Gulf Harbors canals, homes map largely in Zone AE, and many of those are raised or built to flood codes. Higher-ground neighborhoods such as Beacon Square, Jasmine Estates, and much of River Ridge, plus newer subdivisions on the city's east side, sit in Zone X. Roughly 900 homes in the city sit inside the mapped flood zones, which puts the flood question at the center of most riverfront and canal shopping in the 34652 area.
What Flood Insurance Actually Costs in New Port Richey
Here is the number every buyer really wants. Under FEMA's Risk Rating 2.0, flood insurance is priced property by property, so a county average tells you the ballpark and the quote at your address tells you the truth. As planning ranges, Pasco County premium data shows Zone AE policies averaging about $1,665 a year and Zone X policies averaging about $619 a year, with the county-wide average around $1,221 across more than 23,000 active policies. In 2026 Florida dollars, a mid-sized home in Zone AE commonly quotes between about $1,500 and $4,000 or more a year, while a Zone X home usually lands between about $500 and $900 a year on a Preferred Risk Policy.
Risk Rating 2.0 is what makes two houses in the same zone quote so differently. The single biggest driver is the height of the lowest floor relative to the base flood elevation: an elevated home can beat a ground-level neighbor by thousands of dollars a year. After that come the distance to and type of the nearest water, how often that water floods, the building's age and construction, and the coverage limits and deductible you choose. In practice, two same-street AE homes can differ by $1,400 to $2,800 a year, which is exactly why you get a real quote before you fall in love with a price per square foot.
New Port Richey residents also get a discount that helps. The City of New Port Richey holds a Class 6 rating in the NFIP Community Rating System, worth a 20% discount on flood premiums in the Special Flood Hazard Area, and unincorporated Pasco County holds a Class 5 rating, worth a 25% discount in the floodplain and 10% outside it. FEMA applies those discounts automatically to NFIP policies, so the planning ranges above already reflect them in most cases. The base flood elevation near the coast runs about 10 feet on the published case-study projections, and New Port Richey's building code requires new homes in the floodplain to be elevated at least one foot above it, which is why newer construction tends to quote better than a ground-level bungalow from the 1950s.
When Flood Insurance Is Required, and When It Is Not
The requirement is simpler than it sounds. If you finance a home with a federally backed or federally regulated mortgage, which covers almost every conventional, FHA, VA, and USDA loan, and the home sits in a Special Flood Hazard Area, an A or V zone on the flood map, flood insurance is required and it stays required for the life of the loan. The required coverage is the lesser of your loan balance or the maximum NFIP coverage, $250,000 for the building and $100,000 for contents, and a lender can force-place a policy if you let one lapse.
Outside the floodplain, in Zone X, federal law does not require flood insurance, though some lenders and condo associations still ask for it. For most river-town buyers we still recommend a Preferred Risk Policy, because it is cheap, a few hundred dollars a year, and it covers the flash-flood and storm events that do not wait for a map. Cash buyers have no lender mandate at all, but the premium still matters twice: it shapes the monthly cost of owning the home, and it shapes the pool of future buyers when you sell.
Elevation Certificates: The Document That Moves the Price
If there is one document that changes the flood math on a New Port Richey home, it is the elevation certificate. A licensed surveyor, engineer, or architect completes the FEMA form, recording the height of the lowest floor, the lowest adjacent grade, and the elevation of machinery relative to the base flood elevation at that parcel. Under Risk Rating 2.0 an elevation certificate is not strictly required just to get coverage, but it can lower the premium when it shows the home is elevated above the base flood elevation, and it is the single most useful way to compare two homes in the same zone. A certificate typically costs about $400 to $700 in Florida, and before you pay for a new one, ask whether the seller, their lender, or Pasco County's permit office already has a copy on file.
This is where the flood question becomes a negotiating tool. When a home's certificate shows a lowest floor well above the base flood elevation, the premium is a minor line item, and the elevated home can be cheaper per month than a lower-priced ground-level house a block away. Ask the seller for their certificate and their current policy declarations page before you write an offer. Most will hand them over; a seller who cannot find them is telling you something worth knowing.
How to Build Flood Into Your Offer: The Buyer's Playbook
After more than 45 years in the Tampa Bay market and over 1,000 homes sold, most of them right here in west Pasco, we have watched the flood question go from an afterthought to a first-class line item in every contract we write. Buyers who handle it well do the same five things, in the same order:
- Get the flood disclosure. Florida's flood disclosure law, in effect since October 1, 2024, requires the seller to provide a written disclosure of known flood damage, flood insurance claims, and any federal disaster assistance received. Read it, ask follow-up questions, and keep it with your contract.
- Pull the certificate and the policy page before you offer. The elevation certificate plus the seller's current declarations page tells you the premium truth without waiting for a quote.
- Get your own quote at the exact address. Use an NFIP agent or the county data, not a ZIP-level average, and fold the number into the monthly payment you qualify for.
- Compare homes on elevation, not just price. A slightly higher-priced elevated home can win on total monthly cost, and that is the comparison that matters.
- Negotiate in writing. Closing-cost credits, rate buydowns, and flood-policy credits are ordinary 2026 concessions in this market, and a seller who knows the flood file is asking a fair price will often structure one before inspections.
Keep your contingencies. In New Port Richey's balanced market you do not have to waive inspection, appraisal, or insurance to compete, and a smart seller prefers a buyer who can actually close. The buyer who walks in knowing the zone, the elevation, and the premium is the buyer who negotiates from strength.
Why Buyers Still Choose New Port Richey
The flood question is a number, not a verdict. What brings buyers to this town is the river life the map protects: the riverfront amphitheater and splash pad at Sims Park, the restored Hacienda Hotel anchoring a downtown that has come back to life, farmers markets and live music in Railroad Square, kayaks and paddleboards on the Cotee River Paddling Trail from downtown out to the Gulf, and the canals of Gulf Harbors where you can tie a boat up at your own dock. James E. Grey Preserve puts 80 acres of wetlands within walking distance of downtown. When you weigh all of it, a flood zone is one line in the budget, not a reason to cross the whole town off your list. For the neighborhoods, dining, parks, and daily life in depth, start with our New Port Richey community guide.
The Bottom Line from Team Virgadamo
Here is how we would advise our own family: confirm the zone at the exact parcel, get the seller's elevation certificate and flood disclosure, quote the premium at the address, compare homes on elevation rather than price alone, and negotiate the flood line into the deal like any other cost. Do those things and the flood zone stops being a fear and becomes one more number you understand, which is the whole point of working with someone who actually lives here.
Who you hire truly matters. We are Denise and Paul Virgadamo of Team Virgadamo at Dalton Wade Real Estate Group, and New Port Richey is home turf we have walked for decades, riverfront to floodplain, with over 1,000 homes sold across Pasco, Pinellas, and Hillsborough Counties. Start with our New Port Richey community guide, then let's put a real number on your flood line together. We Live, Love & Sell Tampa Bay!
Ready to buy in New Port Richey?
Let's pull the flood zone, the elevation certificate, and a real premium quote for the exact address before you write an offer. Schedule a free, no-obligation consultation with Paul and Denise Virgadamo.
Explore our communities: